Long-Term Care Insurance Delivers Care at Home
About This Article
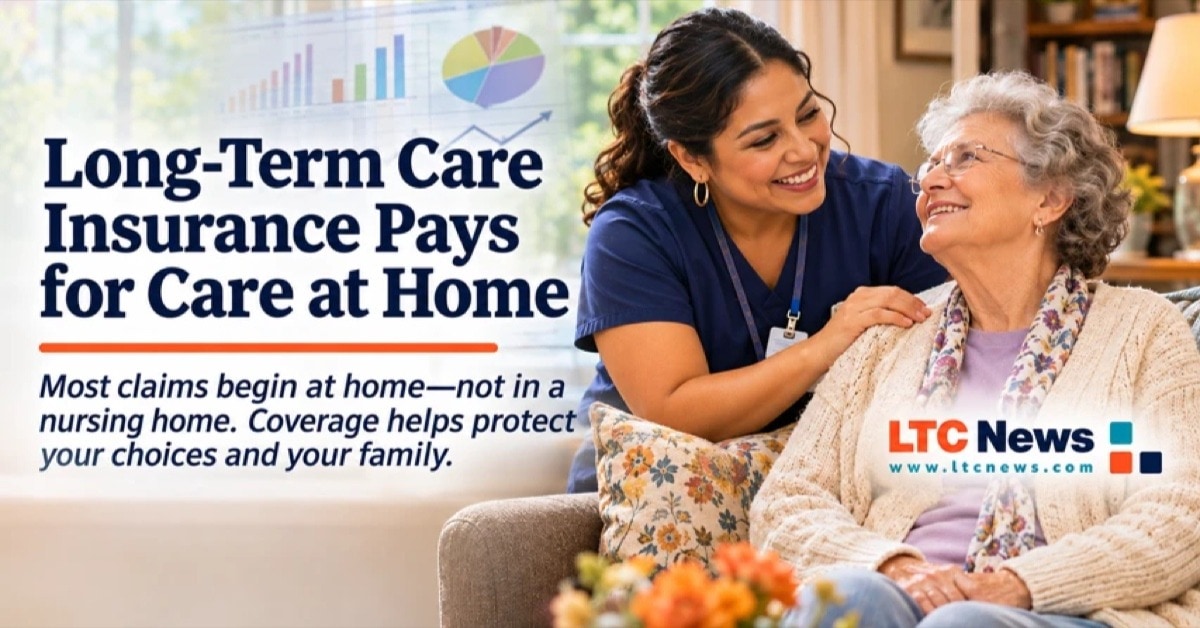
Recent studies show most Long-Term Care Insurance claims start with care at home. While most people think the insurance only pays for nursing homes, the reality is the opposite. Recent data shows that over $17 Billion in benefits were paid to American families.
James Kelly
LTC News staff writer specializing in long-term care and aging.
Aging, chronic health concerns, and extended care are front and center for most of us, either directly or indirectly. You may not think about these things every day or even consider the flu, respiratory viruses, or COVID-19 anymore. Most of us don’t. But for older adults with chronic health problems, and for families with a loved one in a nursing home, these concerns and the COVID-19 virus never fully went away. The pandemic taught families something lasting. Where you get care matters. For most Americans who need long-term care, that place is home.
The pandemic taught families something lasting. Where you get extended care matters. For most Americans who need long-term care, that place is home, which is a good thing, as most research shows that is where most people want to age, in place at home.
Learn More: What is long-term care?
Is COVID-19 still a risk for nursing home residents? Yes. The risk is far lower than in 2020, but it is still there. The early toll was staggering. More than 200,000 nursing home residents and staff died of COVID-19 between early 2020 and early 2022, according to a KFF analysis of Centers for Disease Control and Prevention (CDC) data, as reported by The New York Times.
Deaths dropped sharply after vaccines arrived and infection control improved. Even so, about 3,000 nursing home residents died of COVID-19 between mid-November 2023 and mid-February 2024, according to an analysis of Centers for Medicare & Medicaid Services (CMS) data reported by McKnight’s Long-Term Care News.
Tracking the virus has also become harder. The CDC stopped collecting data on COVID-19 deaths among nursing home residents after the week ending Sept. 29, 2024, according to the AARP Public Policy Institute. Nursing homes still report weekly COVID-19, influenza, and respiratory syncytial virus (RSV) cases to the CDC’s National Healthcare Safety Network.
That could change. In September 2026, The New York Times reported a draft CMS plan that would end the weekly reporting requirement. Consumer advocates warned that respiratory illness still hits residents hard. The American Health Care Association said the reporting adds hours of administrative work for caregivers each week.
Many long-term care facilities have improved how they manage outbreaks. But COVID-19 vaccination rates among nursing home staff have been below 10 percent in recent years, according to CDC figures cited by The New York Times. Families should still ask hard questions about infection control at any facility they consider.
The good news is that most long-term care is delivered at home today.
Care at Home, How Common Is It?
What percentage of long-term care is provided at home? Most of it. Nursing homes are only one part of long-term care, and a shrinking one.
Recent data show the shift:
- Long-Term Care Insurance: About 70 percent of new Long-Term Care Insurance claims paid in 2019 began with the policyholder receiving care at home, up from 52 percent in 2014, according to the American Association for Long-Term Care Insurance.
LTC News data indicates that the trend continues. Nick DeFrank, Vice President at LTC News, notes search interest in the Caregiver Directory is still dominated by in-home care.
Search activity on the LTC News Caregiver Directory continues to show that most families are looking for in-home caregivers, reflecting the strong desire of older adults to remain in the comfort of their own homes as they age. Adult day care centers and assisted living communities remain close behind in demand, highlighting the need for flexible care options that support independence while providing supervision and social engagement." — Nick DeFrank, Vice President, LTC News.
DeFrank notes that searches for memory care services continue to grow as the aging population expands and more families face the challenges of Alzheimer's disease and other forms of dementia.
These trends underscore the increasing demand for a full continuum of long-term care services across the country, but starts with in-home care." — Nick DeFrank.
Medicaid recipients, those with limited financial resources, are now receiving in-home care as well, where allowed. In 2023 (the most recent data), 87.1 percent of Medicaid long-term care recipients received home and community-based services (HCBS), according to CMS. HCBS also accounted for 63.8 percent of Medicaid long-term care spending. That year, 8.4 million people received HCBS, compared with 1.5 million who received institutional care.
Is the need for long-term care real? Yes, it is. HHS estimates 56 percent of Americans turning 65 will need long-term care, defined as help with at least two of six activities of daily living (ADLs) for 90 days or more, or substantial supervision due to severe cognitive impairment.
Long-Term Care Insurance has become a big part of helping people remain at home. LTC Insurance policies pay real claims to real families, and the dollars keep growing. Insurers reported about $17 billion in claims in 2024, up more than 80 percent since 2015, according to an analysis by the actuarial firm Milliman of data from the National Association of Insurance Commissioners (NAIC).
Policyholders also tend to get more care. A study funded by America’s Health Insurance Plans (AHIP) found people with Long-Term Care Insurance received 35 percent more hours of care than people without coverage. They received almost twice as much paid care and only 10 percent less unpaid help from family.
Learn More: LTC News Comprehensive Guide to In-Home Care
Do Women Need Long-Term Care More Than Men?
Yes. Women generally live longer than men and are more likely to need care, often for longer periods, including at home. Although men are living longer, that increased lifespan is increasing their need for long-term care, as their healthspan is not keeping up.
The HHS estimates that 64 percent of women turning 65 will need long-term care, compared with 49 percent of men. Insurance claims show the same pattern. Women accounted for 68 percent of new Long-Term Care Insurance claims in 2017, according to the most recent data from the AALTCI.
DeFrank said requests for assistance with Long-Term Care Insurance claims through LTC News and its partnership with Amada Senior Care suggest the gap between men and women needing extended care may be narrowing, indicating men are beginning to catch up with women in using long-term care services. While DeFrank emphasized that this is not based on a scientific study or formal research, it is a trend he has observed anecdotally from claim-related inquiries and caregiver requests over time.
👉 — File a Long-Term Care Insurance Claim.
Where does Long-Term Care Insurance Pay for Care?
There are some people who still think LTC Insurance just pays for nrusing homes. Not true. Most comprehensive Long-Term Care Insurance policies sold today pay for extended care in many settings. That includes:
- Home care, from help with daily activities to skilled nursing at home
- Adult day care
- Assisted living
- Memory care
- Nursing home care
Choice is the point. You and your family decide where you receive care and who provides it. You don’t have to settle for whatever your savings or Medicaid will allow. Nor do you have to depend on your adult children to juggle their schedules to help you.
Matt McCann, a leading expert on long-term care planning, agrees that the people he speaks with want choice and the ability to stay at home.
After helping families plan for long-term care for decades, I've found that most people tell me they want to age in place for as long as possible. Home is where the memories are, where family gathers, and where people feel most comfortable and independent. If a time comes when living at home is no longer safe or manageable, many say they would prefer a high-quality assisted living community that offers both support and dignity. But for most Americans, the goal is clear: stay at home as long as possible because home is where the heart is, and where family remains closest." — Matt McCann, CLTC.
Coverage depends on the policy. Older policies and some short-term cash indemnity plans may limit where you can use benefits, so read your policy or ask a qualified Long-Term Care Insurance specialist before you need care.
Why Does Long-Term Care Belong in Your Retirement Plan?
Long-term care costs can drain the savings you’ve built over a lifetime. You may have spent decades building a 401(k), IRA, SEP-IRA, or 403(b). One long care need can undo much of that work.
Protecting those accounts is part of planning for a longer life. Most people want to choose how and where they receive care. They also want to avoid draining their assets or leaving the work to a spouse or adult children. Long-Term Care Insurance lets you make those decisions while you are still healthy enough to qualify.
Experts say the bottom line is that, since you probably want to remain at home, an LTC policy will help fund that desire. However, if you need a facility, like assisted living, those costs will not wipe out your assets.
What Does Long-Term Care Insurance Cost?
Experts tell LTC News that many people think LTC Insurance is more expensive than it really is. Premiums depend on your age, health, the benefits you choose, and the insurer. Many people find a policy they can afford. Others find premiums too high, especially if they wait until their 60s or 70s. LTC News data shows most people express interest in Long-Term Care Insurance between the ages of 47 and 67.
LTC Insurance comes in a variety of policy types from leading insurance companies. Traditional policies, hybrid long-term care policies combining life insurance and long-term care, and short-term care plans each have trade-offs.
Long-Term Care Insurance is medically underwritten. Each insurer looks at your health history differently, so one company may approve you while another declines. A qualified Long-Term Care Insurance specialist can compare insurers and match you with the one most likely to approve you at the best price.
Are Long-Term Care Insurance premiums tax-deductible? Yes, that is another benefit of LTC Insurance. If you have a Health Savings Account you can use the pre-tax money in those plans to pay for your LTC Insurance premium.
Aging at Home is Often the Goal
For most older adults, aging at home is more than a preference. It is a goal that helps them maintain independence, stay connected to their community, and continue the routines that bring comfort and purpose to daily life. Staying in a familiar environment can help reduce stress and provide a greater sense of control during the aging process.
Aging at home also lets seniors stay close to family, friends, neighbors, and local activities that matter to their quality of life. Familiar surroundings can be especially beneficial for those experiencing memory loss or cognitive decline, as consistency and routine often help reduce confusion and anxiety.
“For most people, home represents a lot more than just a physical place,” said Dr. Julie Daftari, chief medical officer of UnitedHealthcare Medicare & Retirement. Strong support at home matters too.
Social connection is one of the strongest predictors of whether living independently is sustainable." — Dr. Julie Daftari.
With the right planning and support services, many older adults can safely remain at home even when health and age challenges arise. In-home caregivers, home modifications, adult day care programs, and Long-Term Care Insurance benefits can all help make aging in place a realistic and sustainable option.
Discover More: The LTC News Caregiver Directory allows you to search over 80,000 caregivers and long-term care facilities nationwide, including the District of Columbia, Puerto Rico, and the U.S. Virgin Islands.
While aging at home is not always possible for everyone, it remains the preferred choice for most Americans. Preparing in advance for future care needs can help ensure that older adults have the flexibility to remain at home as long as possible while preserving both their independence and dignity.
Learn More: LTC News Long-Term Care Insurance Learning Center

Sponsored